The 5 biggest worries we hear about retirement
-
“Will my savings last?”
This is the one we hear most. It starts with knowing where each month’s income will come from: Social Security, any pension and your savings. A fixed annuity can be one steady piece of that. If you want a check for life, some contracts offer a lifetime income option for a yearly fee.
-
“What if the market drops right when I retire?”
The insurance company sets a fixed annuity’s rate for the years you choose. A market drop doesn’t change it, and your money isn’t in the stock market.
-
“Will my money be locked up?”
Many contracts let you take out about 10% a year with no surrender charge, often starting in year two. Taking out more in the early years costs a surrender charge that shrinks each year, then goes away. Keep your emergency money outside the annuity.
-
“If I die, does the insurance company keep my money?”
Not with a fixed annuity. The account value goes to the people you name. They owe income tax on the growth. On many contracts, the surrender charge goes away at death.
-
“I’ve heard annuities are bad.”
“Annuity” covers a whole family of products, and they work very differently. Some are tied to the stock market and can lose value. A fixed annuity is the simplest kind: a set rate for a set number of years.
What an annuity is
An annuity is a contract with an insurance company. You put money in, either all at once or over time. In return, the company agrees in writing to certain terms. Depending on the kind, that can be a set interest rate, protection when the market drops, income for life, or a mix.
The two kinds we offer, fixed and fixed indexed annuities, don’t put your money in the stock market.
An annuity is an insurance contract. It isn’t a bank account, and it isn’t FDIC-insured. Its guarantees are backed by the insurance company that issues it.
How a fixed annuity works
You put money in, and the insurance company credits a set interest rate for a set number of years, often between 2 and 10. You know the rate and the length before you sign, and a market drop doesn’t change them.
Leaving before those years are up can cost a surrender charge (more on that below). When they’re up, you can renew at the rate offered then, move the money or take it out.
It’s the simplest kind, and a good fit if you like knowing your rate ahead of time. You may see it called a MYGA, short for multi-year guaranteed annuity.
Fixed indexed annuity: interest tied to an index, with a floor underneath
Your interest is tied to a market index, like the S&P 500. An index is a score that tracks a group of stocks. The S&P 500 tracks 500 large U.S. companies. Your money isn’t in the stock market. The index is only the yardstick.
In a year the index goes up, the insurance company adds some or all of that gain to your account as interest, up to a limit it sets, called a cap. In a year the index goes down, you get 0% interest, and your account value doesn’t drop because the index did. It can still go down for other reasons: taking out more than the contract allows during the surrender period, or paying fees for optional add-ons. Once interest is added, a later down year can’t take it away.
If you want a check every month
Fixed and fixed indexed annuities can both be set up to pay you income. Some contracts offer a lifetime income option that keeps paying for the rest of your life, if you stay within its withdrawal rules. It’s usually an add-on with a yearly fee. The checks come out of your own account value first. If that ever runs out, the insurance company keeps paying.
Think of an annuity like a Christmas tree. The plain tree is the basic contract. Add-ons, like lifetime income, are the lights and ornaments. Each one costs something, so add only what you’ll use.
There’s also an immediate annuity, which turns a lump sum into monthly payments that start right away. The trade-off is that once payments start, you usually can’t take the lump sum back out, so it’s only for money you’re sure you want as income. You can choose options that keep paying your spouse, or that keep payments going to your family for a set number of years.
Every income guarantee is backed by the insurance company that issues the contract.
What to know before you decide
None of this is fine print. It’s how annuities work, and you should know it before you sign.
- It’s for money you can leave alone for a while. Most annuities have a surrender period, commonly 3 to 10 years. If you take out more than the contract allows during that time, there’s a surrender charge. The charge gets smaller each year, then goes away. Some contracts also have a market value adjustment, which can raise or lower what you’d get if you leave early. We’ll point it out if a contract has one.
- Keep your emergency money separate. The insurance companies insist on it too. They limit how much of your savings can go into an annuity.
- The guarantees come from the insurance company. That’s why the company’s financial strength matters. We’ll look up its rating together before you decide.
- You get time to look it over. In Oregon, the free-look period is at least 10 days after your contract arrives, and some contracts give more. If you change your mind in that window, you can return the contract without a penalty. Other states set their own free-look rules, and your contract shows yours.
- You can read up on your own. You can read the Oregon Division of Financial Regulation’s guide, Is your annuity a fit? You can also ask the Division for a free annuity Buyer’s Guide, or ask us and we’ll send you one.
- We don’t post rates or “what if” projections here. They change often and depend on your age and the contract. We go over them one-on-one, starting with the numbers the insurance company guarantees.
How it works
-
We talk first
Call or text. We can talk by phone, by video, or at the Woodburn office by appointment. Our first question is simple: do you want income, growth, or both? Then we’ll ask about your Social Security, any pension, your monthly bills, your savings, and when you might need the money. In Oregon, we’re required to understand your situation before we recommend anything.
-
You see your options in writing
We compare contracts from several insurance companies we’re authorized to represent. For each one, you’ll see what the insurance company guarantees and what it doesn’t, what it costs to leave early, and the company’s rating. You’ll also get a written disclosure about us and how we’re paid, the insurance company’s own disclosure, and the annuity Buyer’s Guide. Take them home and read them at your own pace. Bring anyone you’d like into the conversation: a family member, a trusted friend, or your tax professional. Helping a parent? You’re welcome on every call. The annuity is in your parent’s name, so your parent answers our questions and makes the final decision. Sometimes our answer is that an annuity isn’t the right fit, or that what you already have is fine.
-
You decide, and we handle the paperwork
If you move forward, many applications can be signed electronically from home. A few companies still use paper. We’ll follow up with the insurance company until your contract is issued, then walk you through it when it arrives. Each year when your statement comes, we’re glad to go over it with you.
Already own an annuity?
Bring your latest statement. We’ll walk you through it: what it’s earning, when the surrender period ends, and the difference between your account value and your surrender value. That gap is what it would cost to leave today.
Often the best answer is to keep what you have. If a change ever makes sense for you, we’ll show you in writing what you’d give up first, including any new surrender period.
If someone already helps you with your money, you don’t have to change that. An annuity can sit alongside what you already have.
Who an annuity may fit, and when it may not
It may fit if:
- You like knowing your interest rate ahead of time.
- You have savings you won’t need for several years.
- You want part of your savings protected when the market drops, and you’re OK with capped growth on that part.
- You’re within about 10 years of retirement, or already retired.
- You’d like a steady monthly check to go with Social Security or a pension.
- You have money in an old 401(k) from a past job and want to understand your choices, including leaving it where it is.
- You already own an annuity and want someone to explain it.
It may not fit if:
- You may need this money in the next few years, or it’s your emergency fund.
- You want every bit of the market’s upside.
- Putting money in would leave you with too little cash on hand.
- Your current annuity or life insurance policy still has surrender charges, and switching would cost you more than it gains.
- You’ve just been through a big change, like losing a spouse, and haven’t decided what you need yet. The money can wait while you decide.
Why talk with us
- In Oregon, every agent follows the same annuity rule. Here’s what it means for you. Oregon’s annuity best-interest rule requires any agent who recommends an annuity to act in your best interest and not put their own pay ahead of yours. Other states have their own versions of this rule. So we have to understand your money and your goals. We have to explain the features that matter: surrender charges, fees and how interest is added. And we have to write down why we recommended what we did. We’ll explain that reason to you before you decide. Gilbert has completed the annuity training Oregon requires, and each insurance company requires its own product training before he can offer its contracts.
- You’ll know how we’re paid. Before we recommend anything, you’ll get a short written form showing which kinds of annuities we’re licensed to sell and how we’re paid. If you buy, the insurance company pays our commission. It isn’t taken out of the money you put in, and you don’t pay us a separate fee. The company builds its costs, including our commission, into the contract’s terms. You can ask us for an estimate of our commission on any contract we show you.
- What’s guaranteed comes first. You’ll see the numbers the insurance company guarantees before any “what if” numbers.
- English or Spanish. Hablamos español. By phone, by video, or at the Woodburn office by appointment.
Looking for life insurance that also builds cash value? That’s indexed universal life (IUL). It’s life insurance, not an annuity. Read the IUL guide →
Common questions
Tap a question to see the answer.
Can I lose money in an annuity?
It depends on the kind, and on how you use it. With a fixed annuity, your rate is set for the years you chose, so a market drop doesn’t change it. With a fixed indexed annuity, your account value doesn’t go down when the index does. With either kind, you can end up with less than you put in. That can happen if you take out more than the contract allows during the surrender period, or if you pay for optional add-ons. Every guarantee depends on the insurance company that issues the contract. That’s why an annuity is for money you can leave alone, and why we’ll show you the charges in writing first.
If I pass away, does the insurance company keep my money?
Not with a fixed or fixed indexed annuity. The account value goes to the beneficiaries you name, and on many contracts the surrender charge goes away at death. Your beneficiaries pay income tax on the growth. The worry comes from one kind of income annuity, where payments stop when you die. If you choose an immediate annuity, you can pick options that keep paying your spouse or keep payments going to your family for a set number of years.
Can I get to my money?
Yes, with limits. Many contracts let you take out around 10% of your value each year, often starting in the second year, with no surrender charge. Taking out more during the surrender period costs a charge that shrinks each year. Many contracts also waive the charge in certain situations, like an extended nursing-home stay. That’s why we’ll ask when you might need the money before we pick how many years the contract runs, and why your emergency fund stays separate.
What happens when my fixed annuity’s years are up?
You can usually renew at the rate offered then, move the money to another contract, or take it out. What happens if you do nothing depends on your contract, so ask us before that date and we’ll go over your choices. Growth you take out is taxed as income, and your tax professional can tell you how that affects you.
What does it cost? Are there hidden fees?
The basic contract usually has no yearly fee. If you buy, the insurance company pays our commission, and it isn’t taken out of the money you put in. The company covers its costs, including our commission, through the contract’s terms, like the cap and the surrender schedule. Optional add-ons, like lifetime income, usually have a yearly fee. You’ll see the costs in writing before you decide.
How do I know the insurance company will be there?
Every guarantee in an annuity is backed by the financial strength and claims-paying ability of the company that issues it. Independent rating agencies grade those companies. We’ll look up the rating of any company we show you, together, before you decide.
I already have an annuity. Should I keep it?
Often, yes. Bring your statement, and we’ll explain what it’s earning, when the surrender period ends, and what leaving today would cost. If a change ever makes sense, you’ll see in writing what you’d give up first, including any new surrender period. We don’t charge for the review.
How are annuities taxed?
In general, interest isn’t taxed while it stays in the annuity. When you take it out, the growth is taxed as income, and taking money out before age 59½ can mean an extra 10% IRS tax. If the annuity holds IRA money, your IRA’s tax rules apply, and the annuity doesn’t add any extra tax benefit. Your tax professional should weigh in on your situation, and we’re glad to include them.
Is there an age limit, a minimum, or a medical exam?
Most fixed and fixed indexed annuities don’t require a medical exam, though some ask whether you live in a nursing home. Many can be issued into your 80s. Minimums vary by contract, and some start at a few thousand dollars. At older ages, how long the surrender period runs and how easily you can reach your money matter most, and we’ll weigh that together.
Under 65 and need your own health insurance? We help with that too. See how it works →
Questions about your retirement income? Let’s talk it through.
Call or text. English or Spanish. Bring your questions, and your statements if you have them.
Monday–Friday 9–5:30, Saturday 10–3, Pacific time. Closed Sunday.
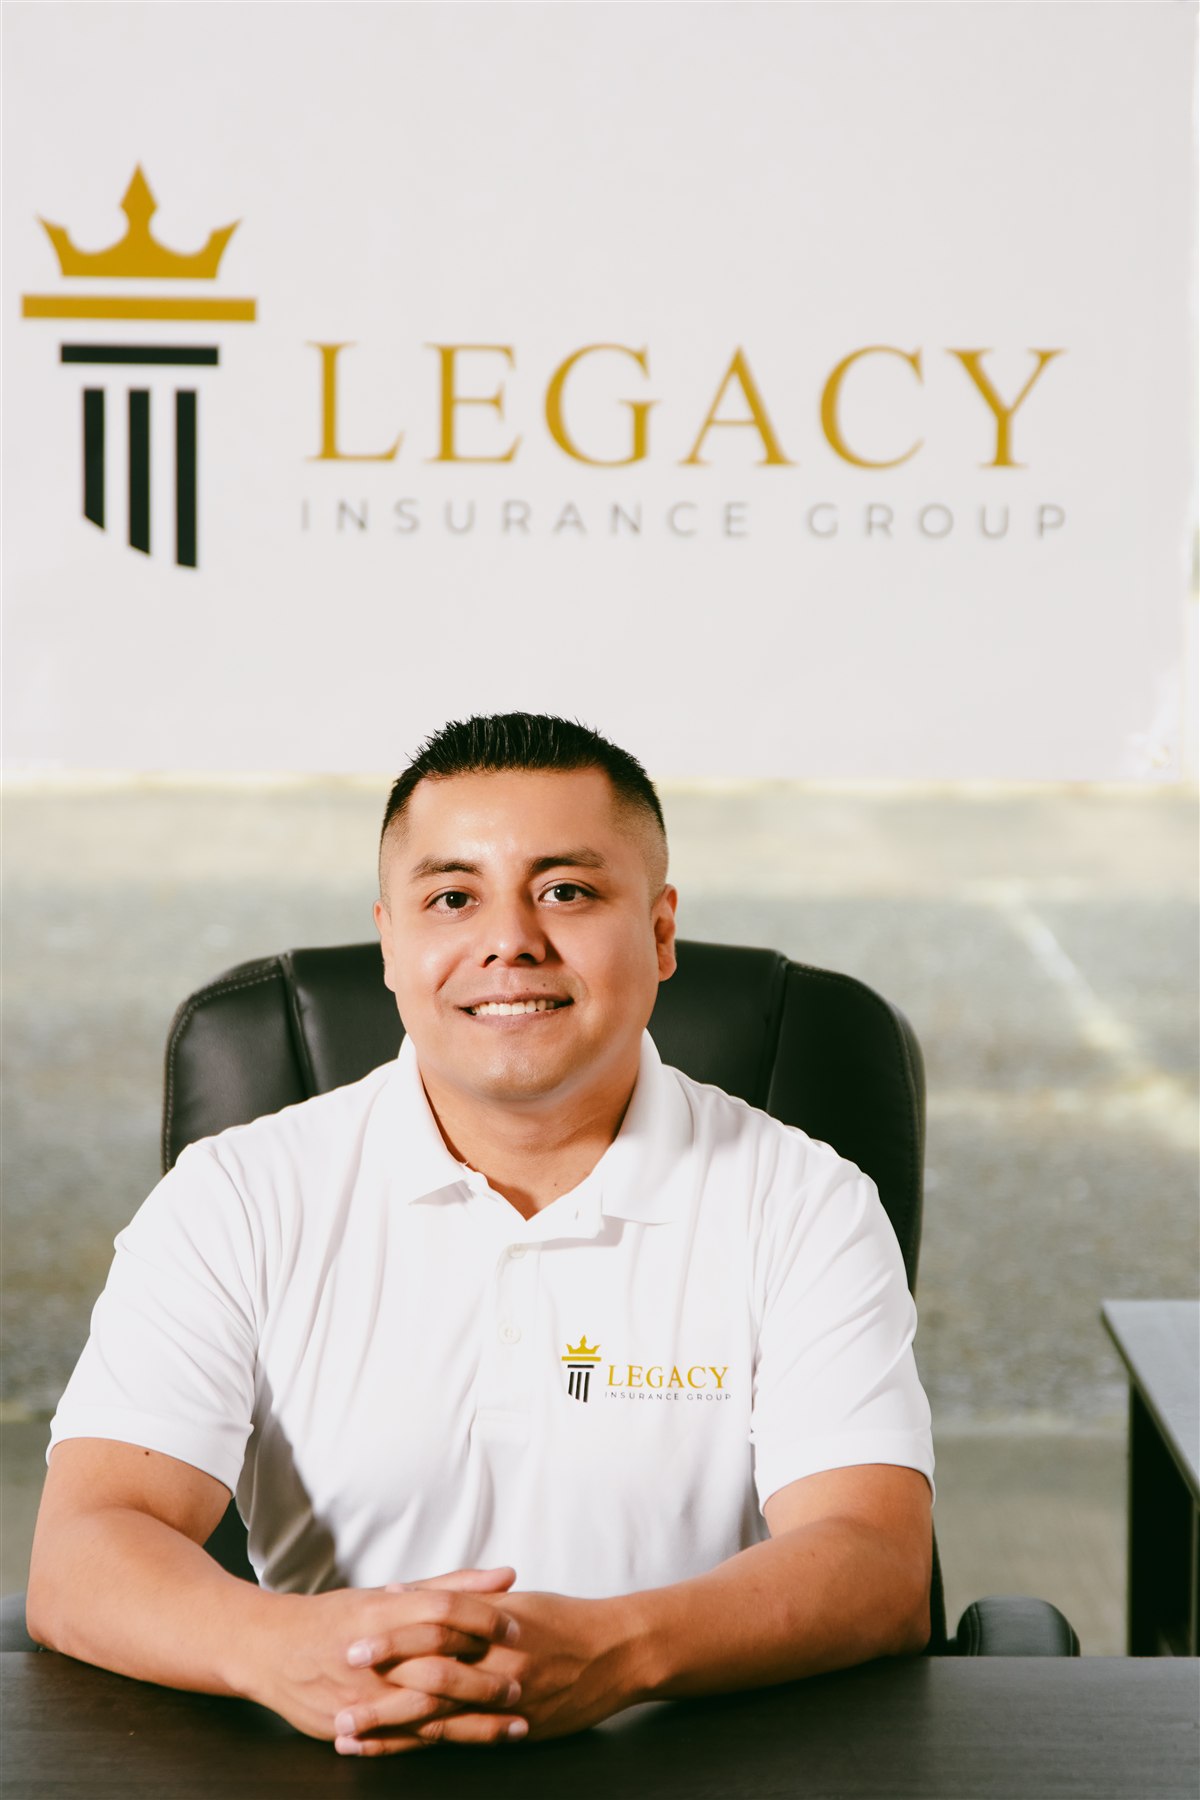
Gilbert Lopez — Founder of Legacy Insurance Group in Woodburn, Oregon. Health & Life Insurance Agent, NPN 16945680. He works with clients in English and Spanish, by phone, by video, or at the Woodburn office by appointment. Call 971-444-6449 or text "info" to the same number. See all our coverage options →
Disclosures
Reviewed October 2026 by Gilbert Lopez, licensed insurance agent, NPN 16945680 (verify at NIPR).
Legacy Insurance Group is an independent insurance agency in Woodburn, Oregon. Annuities are insurance contracts issued by insurance companies. They aren’t bank deposits, aren’t FDIC-insured, and aren’t guaranteed by any bank or government agency. Guarantees depend on the financial strength and claims-paying ability of the issuing insurance company.
Fixed indexed annuities don’t place your money in the stock market or in any index; the S&P 500 is named only as an example of an index. Caps and participation rates can change within limits set in the contract. Surrender charges may apply if you take out more than the contract allows during the surrender period. Some contracts also have a market value adjustment. It can raise or lower what you get if you surrender early. Withdrawals before age 59½ may face a 10% IRS additional tax. Optional riders (add-ons) may cost extra. Contract terms, free-look periods and features vary by company and state.
A free annuity Buyer’s Guide is available from the Oregon Division of Financial Regulation or from us. The agent’s commission is paid by the issuing insurance company. This page explains general features. It isn’t an offer or a recommendation for any one person. We’re licensed insurance agents, not tax or legal professionals.
Questions or complaints about an insurance agent or company: Oregon Division of Financial Regulation, dfr.oregon.gov, 888-877-4894.